Insurance guide
Filing a roof insurance claim in Memphis, step by step
From the first photo to the final check: how a roof claim works, and where homeowners lose money.
By Cora Padgett, Roofing Guides Editor Updated October 2026
We answer 24/7 across Memphis and Shelby County
Quick answer
To file a roof insurance claim in Memphis, document the damage with dated photos, check your deductible and whether the policy pays replacement cost or cash value, have a roofer inspect before you file, report the claim promptly, and meet the adjuster on the roof. Then compare the carrier's scope with the roofer's, line by line.
Before you file: Is there damage worth claiming?
A claim is only worth filing when there is storm damage whose repair costs more than your deductible. A roofer's inspection answers both halves: whether the damage came from the storm rather than age, and roughly what it will take to fix. If the answer is a few shingles below the deductible, paying for the repair directly keeps a claim off your record.
Our storm damage checklist covers what to look for from the ground first.
Know your policy: Deductibles, replacement cost and cash value
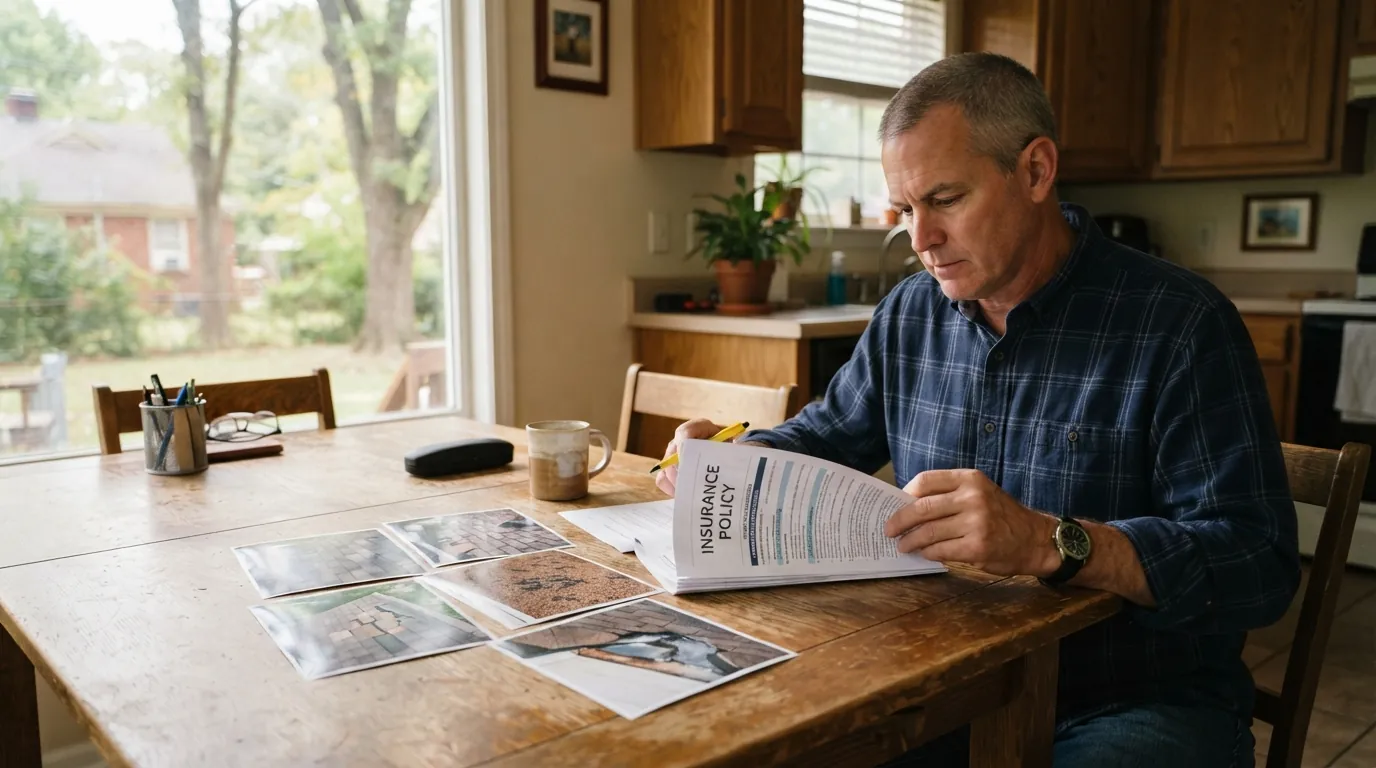
- Deductible. Wind and hail deductibles are sometimes a percentage of the home's insured value rather than a flat amount. Check which you have.
- Replacement cost value. The policy pays to replace the roof, often in two checks: the first minus depreciation, the second after the work is done.
- Actual cash value. The policy pays the depreciated value of the old roof, so an older roof pays out much less.
- Reporting deadlines. Many policies require prompt notice after a storm. Read yours.
Step by step through a roof claim
- Photograph the damage and note the storm date.
- Protect the house: cover openings and keep receipts for emergency work.
- Have a roofer inspect and document the roof.
- Report the claim to your carrier and share the documentation.
- Meet the adjuster on the roof, ideally with your roofer there.
- Compare the carrier's written scope with the roofer's.
- Approve the work; supplements cover items found during it.
- Collect any withheld depreciation after completion, if your policy allows it.
Storm damage and not sure it is worth a claim?
We inspect and document the roof first, so you decide with the facts in hand.
Call (901) 459-6395The adjuster visit
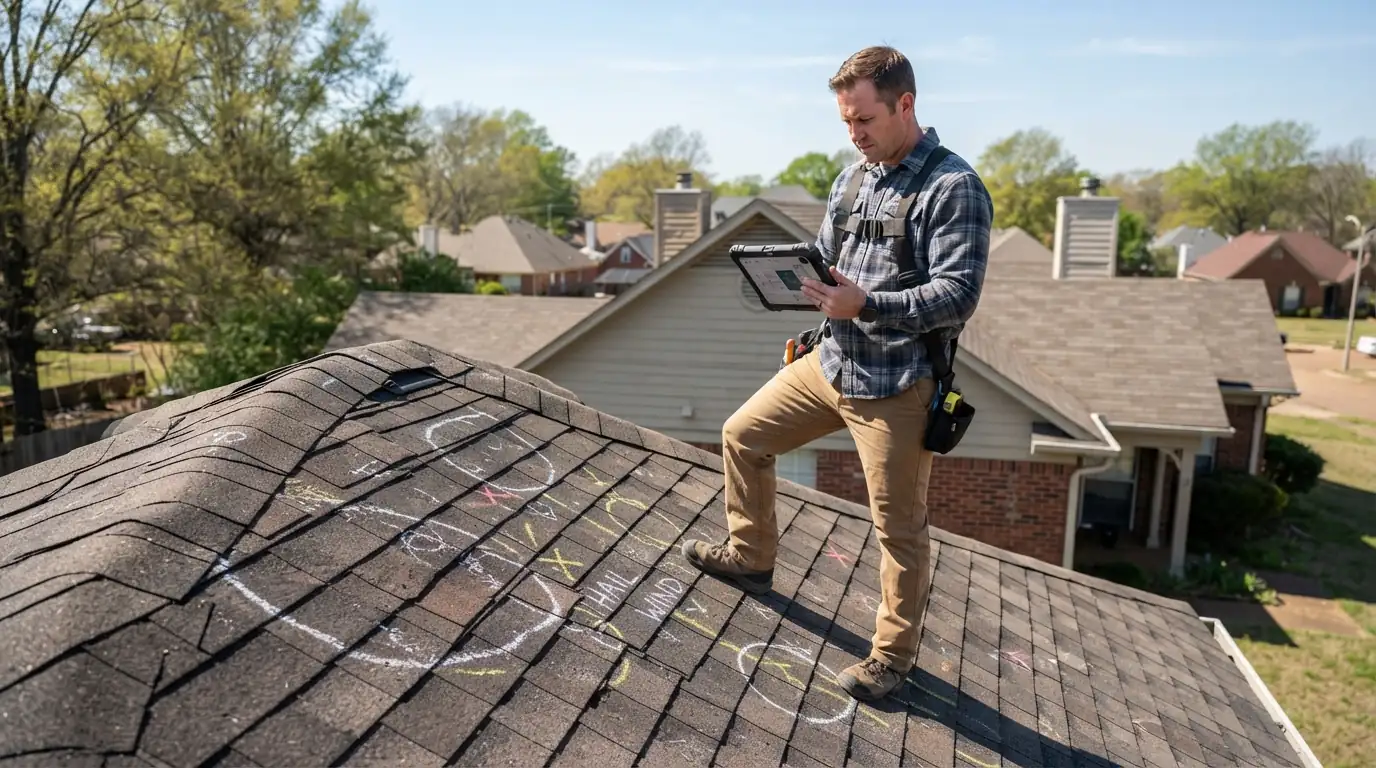
The adjuster works for the carrier and usually has limited time on each roof after a big storm. Having your roofer there means someone points out damage on the far slopes, under the ridge caps and on the soft metals, with the report in hand. Keep the conversation to facts about the roof; coverage decisions belong to the carrier. If the adjuster does not walk the roof, ask whether they will, or whether they will accept the roofer's photos and measurements.
When the scope misses something
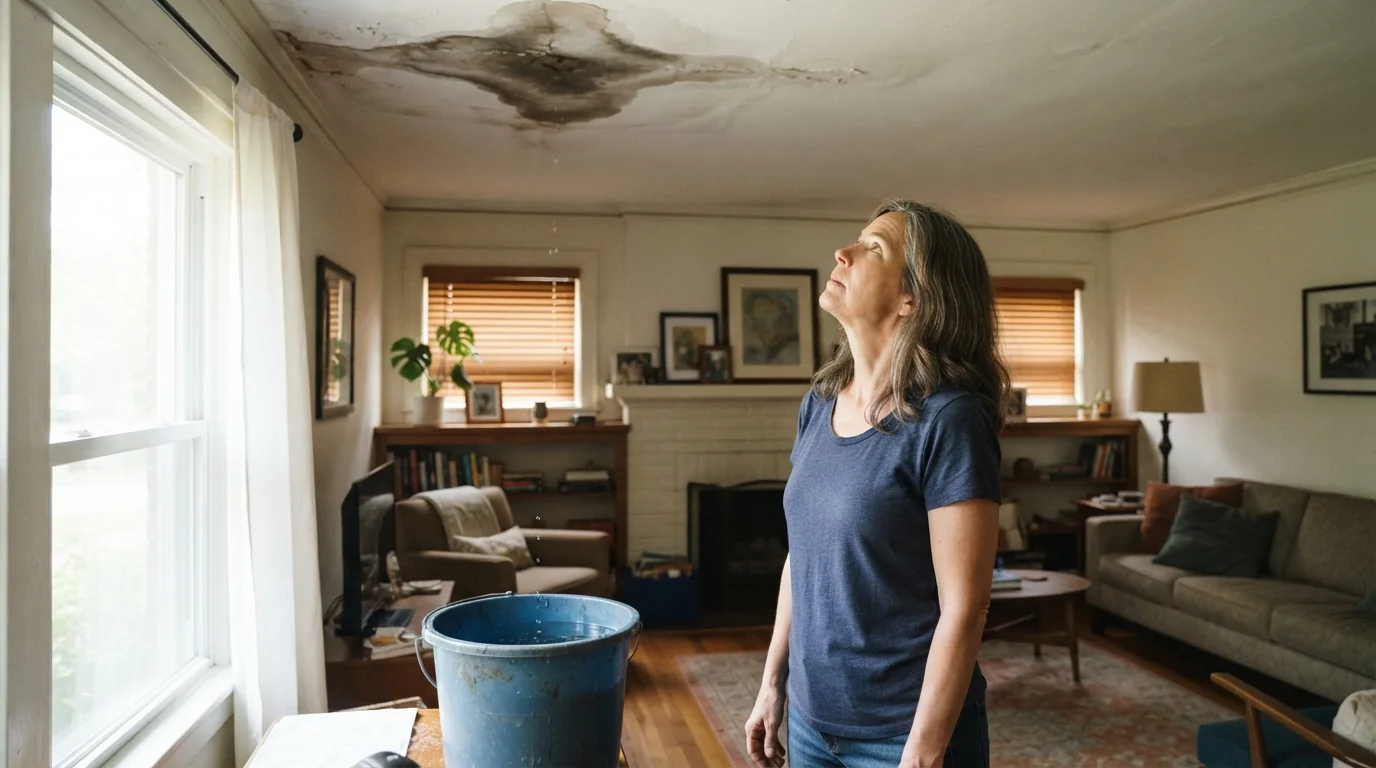
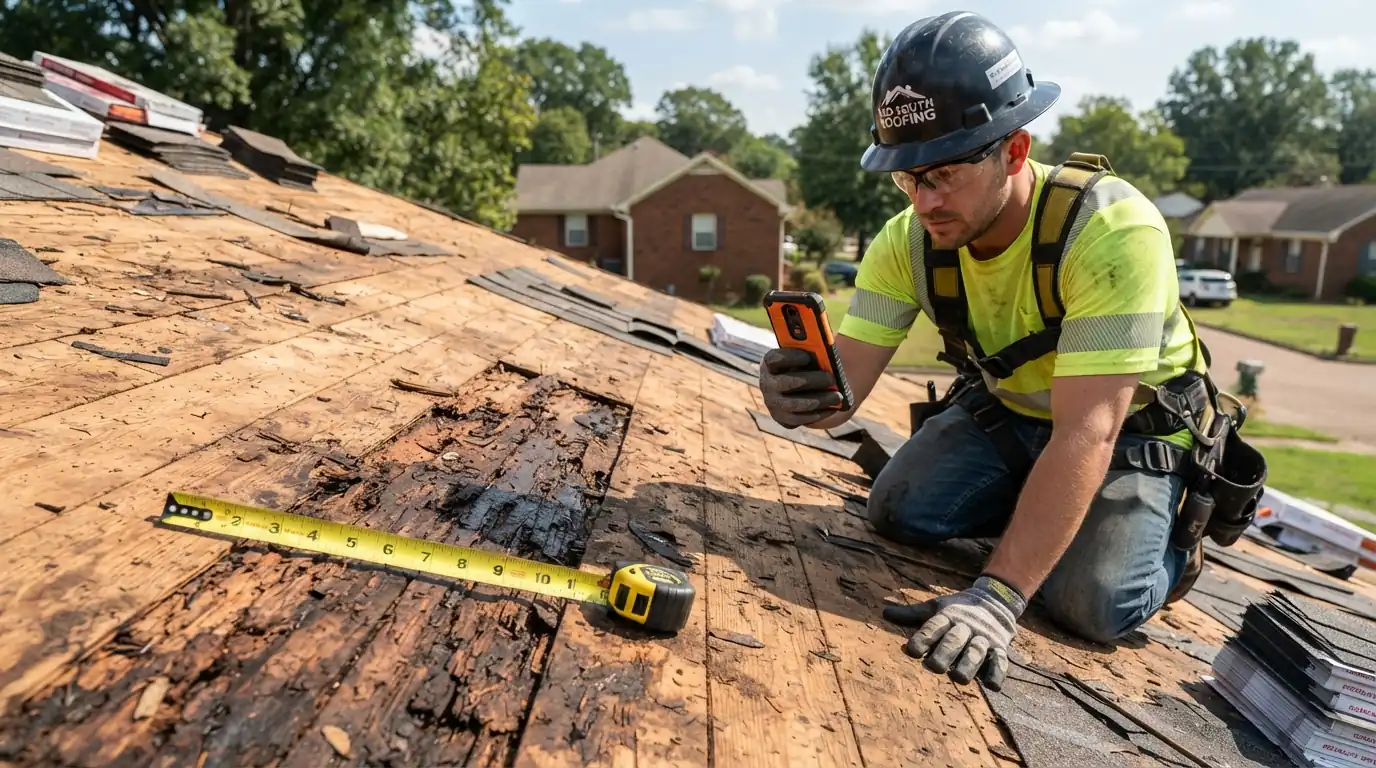
Carrier estimates often leave out items that only show up once the roof is measured or opened: drip edge, starter strip, ridge vent, pipe boots, extra decking or a second layer to tear off. A supplement is a request, with photos and measurements, to add those items. It is a normal part of roof claims, not a dispute, and anything found during tear-off should be photographed before it is covered. Our roof insurance claim help page explains how we prepare them.
Timing after a Memphis storm
After a storm like the one in August 2026 that knocked out power to more than 120,000 MLGW customers, carriers handle a surge of claims at once, and adjuster visits take longer to book. The parts you control are the start and the evidence: report promptly, get the roof documented while damage is fresh, and cover any openings so interior damage does not grow. Most policies expect you to take reasonable steps to prevent further damage.
Mistakes that cost homeowners
- Waiting months to report storm damage
- Signing with a door-to-door roofer before the roof is documented
- Throwing away receipts for tarping or emergency work
- Accepting a scope without comparing it to a roofer's
- Letting damage found during tear-off get covered before it is photographed
FAQ
Roof insurance claim questions
That depends on your carrier and state rules. Ask your agent before you file; the roof documentation is useful either way.
It depends on your policy. Many require prompt notice after a storm, so check the terms and report soon.
It covers sudden storm damage, not age or wear. On a cash-value policy, depreciation reduces the payout on an older roof.
Yes, about the roof's condition and the scope. Coverage and settlement are between you and your carrier.
On replacement-cost policies, part of the payment is withheld until the work is done, then released once you show it was completed.
In most cases, yes. Check your policy and ask the carrier if you are unsure.